Are Bank-Owned Foreclosures Worth It? Pros, Cons, and What Buyers Should Know

Bank-owned foreclosures can look like attractive bargains, especially when a home is listed below the price of similar properties in the area. But a lower asking price does not always mean a lower total cost. Repairs, unpaid bills, title concerns, financing issues, and long closing timelines can turn a seemingly good deal into an expensive project.

So, are bank-owned foreclosures worth it? They can be worth it for buyers who understand the risks, complete careful research, and have enough money and patience to handle unexpected costs. However, they may not be the best choice for buyers who want a move-in-ready home, a simple transaction, or predictable expenses.


What Is a Bank-Owned Foreclosure?

A bank-owned foreclosure is a property that a lender takes possession of after the homeowner fails to make mortgage payments. The lender usually tries to sell the home at a foreclosure auction first. If the property does not sell, ownership may transfer to the lender.

At that point, the home is commonly called an REO property, which means “real estate owned.” The bank or mortgage company then lists the property for sale, often with the help of a real estate agent.

Buying an REO property is different from buying a home directly from a homeowner. The seller is usually a bank, government agency, or mortgage company. The seller may not have lived in the property and may have limited knowledge about its condition.

Bank-owned homes are often sold as is. This means the lender may be unwilling or unable to make repairs before closing. Buyers generally need to inspect the property carefully and decide whether the price reflects the home’s condition.

Unlike buying a property at a foreclosure auction, purchasing an REO home usually gives buyers more time to inspect the property, arrange financing, order an appraisal, and complete a title search. However, the transaction can still involve more paperwork and uncertainty than a traditional home purchase.


Why Do Banks Sell Foreclosed Homes Below Market Value?

Banks are not usually in the business of owning and managing residential properties. Once a lender takes possession of a foreclosed home, it becomes responsible for expenses such as property taxes, insurance, maintenance, security, and possible repairs.

The longer the property remains unsold, the more it may cost the lender. For this reason, the bank may price the home competitively to attract buyers and recover as much of the unpaid loan as possible.

A bank-owned property may also need repairs because it was vacant, neglected, damaged, or poorly maintained before foreclosure. The lender may reduce the price to account for some of these issues.

However, a below-market price is not automatically a bargain. The discount may simply reflect the estimated cost of repairs, a weak location, an unusual layout, legal complications, or limited buyer demand. The important question is not just, “How much is the home discounted?” It is, “How much will the property cost after repairs, fees, financing, and ongoing maintenance?”


Potential Benefits of Buying a Bank-Owned Foreclosure

Lower Purchase Price

The biggest reason buyers consider bank-owned foreclosures is the possibility of purchasing a home below the price of comparable properties. A discount can help buyers enter an expensive market, increase their potential equity, or create room in the budget for renovations.

The actual discount varies widely. Some REO homes are priced close to market value, especially in areas with strong demand. Others may be priced lower because they require major repairs or have been vacant for a long time.

Buyers should compare the property with recently sold homes, not only active listings. A home listed for less than nearby properties may still be overpriced if those properties have better conditions, larger lots, updated systems, or stronger locations.

More Time for Due Diligence

Foreclosure auctions can require quick decisions and may offer little or no opportunity to inspect the property before bidding. An REO purchase is usually closer to a traditional real estate transaction.

Buyers may be able to:

  • Visit the property before making an offer.
  • Hire a professional home inspector.
  • Request an appraisal.
  • Review available property records.
  • Order a title search.
  • Arrange financing.
  • Include inspection or financing contingencies, depending on the seller’s contract.

These protections can reduce the risk of buying a property with serious hidden problems. They do not eliminate risk, especially when the home is sold as is, but they give buyers more information before committing.

Possible Financing Options

A foreclosure auction often favors cash buyers because the payment deadline may be short and the property may not qualify for a traditional mortgage. A bank-owned home, on the other hand, may be eligible for conventional financing or certain government-backed loan programs.

The property’s condition is important. A lender may refuse to finance a home with major safety, structural, electrical, plumbing, or roofing problems. Some loan programs have specific property standards that the home must meet before closing.

Buyers should speak with a mortgage lender before making an offer. A lender can explain whether the property may qualify for the intended loan and whether repairs need to be completed before financing can be approved.

The Property May Be Vacant

Vacant properties can have advantages. Buyers do not usually need to negotiate with an occupant, wait for a seller to move out, or manage a complicated seller’s timeline.

A vacant home may also be easier to tour and inspect. Buyers can often examine rooms, storage areas, exterior spaces, and visible systems without disrupting the previous owner.

However, vacancy can also create problems. A home that sits empty may develop leaks, mold, pest infestations, frozen pipes, overgrown landscaping, or security issues. A professional inspection is especially important when a property has been unoccupied for an extended period.

Possibility of Renovation and Equity Growth

Some buyers purchase bank-owned homes because they want to renovate. If the home is structurally sound and located in a desirable area, improvements may increase its value and make it more comfortable to live in.

Renovation can include cosmetic updates such as paint, flooring, lighting, landscaping, and kitchen improvements. It can also involve expensive work, including foundation repairs, roof replacement, plumbing upgrades, electrical rewiring, or heating and cooling replacement.

The key is to estimate the total renovation cost before making an offer. Buyers should collect contractor estimates and include a reserve for unexpected expenses. Older homes often reveal additional problems after work begins.


The Main Risks of Bank-Owned Foreclosures

The Home Is Usually Sold As Is

When a bank sells a property as is, it generally does not promise to repair defects discovered by the buyer. The seller may also have limited information about what happened in the home before foreclosure.

An inspection may reveal problems with:

  • The roof.
  • Foundation or structural components.
  • Plumbing and sewer lines.
  • Electrical wiring.
  • Heating and cooling systems.
  • Windows and insulation.
  • Water damage or mold.
  • Appliances and fixtures.
  • Driveways, fences, and drainage.
  • Termites or other pests.

A buyer may still request repairs or a price adjustment, but banks often use standard addenda that limit negotiations. Some lenders may reject requests for minor repairs altogether.

Repair Costs Can Be Difficult to Predict

A damaged home may need more than cosmetic improvements. What appears to be a simple renovation can become expensive when walls are opened or old systems are tested.

For example, a buyer may plan to replace flooring but discover water damage underneath. A roof leak may have damaged insulation, drywall, wiring, or framing. A home that needs new paint may also require electrical upgrades before it can safely pass an inspection.

A useful approach is to create three repair estimates:

  1. The cost of immediate safety and habitability work.
  2. The cost of important repairs that should be completed within the first year.
  3. The cost of optional improvements and cosmetic upgrades.

Buyers should also maintain an emergency reserve. Spending every available dollar on the purchase and planned repairs leaves little room for surprises.

Competition Can Reduce the Discount

Bank-owned properties are not always overlooked. Investors, experienced buyers, and other bargain hunters may compete for attractive homes in desirable neighborhoods.

When several buyers submit offers, the lender may request the buyer’s “highest and best” offer. The property can sell for near market value or even above the original asking price.

Competition also makes it easier for buyers to overpay. The excitement of finding a discounted listing can cause people to focus on winning the property instead of calculating its real value.

Before making an offer, determine the maximum price based on comparable sales, repair costs, closing expenses, financing costs, and the desired amount of equity. Do not raise the offer simply because another buyer is interested.

The Process May Move Slowly

Banks often use asset managers, servicing companies, attorneys, and listing agents to handle REO properties. Offers may need to pass through several levels of review.

As a result, the seller may take longer to respond than a typical homeowner. The bank may request additional documents, change deadlines, require specific forms, or reject contract language that buyers commonly expect.

A delayed response can create problems with mortgage rate locks, moving plans, inspections, and temporary housing. Buyers should remain flexible and avoid making nonrefundable commitments until the purchase is more certain.

Title and Property Records Still Matter

A completed foreclosure may remove certain mortgage interests, but buyers should not assume that every possible title or property issue has disappeared. There may still be unpaid property taxes, municipal charges, homeowner association assessments, judgment liens, boundary disputes, code violations, or recording problems.

A professional title search can identify potential issues before closing. Buyers should also consider title insurance, subject to the terms and availability in their location.

It is also important to check public records for permits, past renovations, building violations, flood information, and property taxes. Requirements vary by state and local government, so buyers may benefit from working with a title company, real estate attorney, or qualified real estate professional.


How to Decide Whether a Bank-Owned Home Is Worth It

Compare the Total Cost

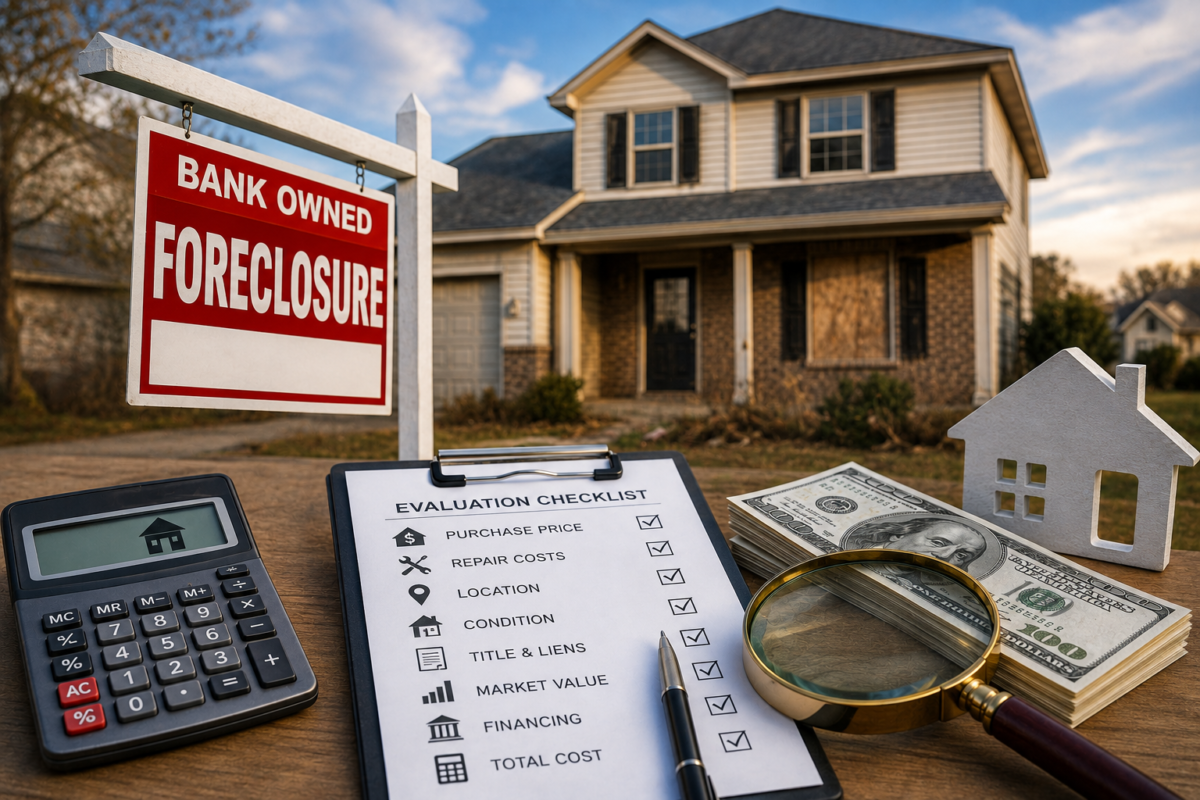
The purchase price is only one part of the financial calculation. Estimate the following costs:

  • Purchase price.
  • Down payment.
  • Closing costs.
  • Inspection and appraisal fees.
  • Immediate repairs.
  • Renovation materials and labor.
  • Utility reconnection or deposits.
  • Property taxes and insurance.
  • Homeowner association charges.
  • Mortgage interest.
  • Temporary housing or storage.
  • Emergency repair reserves.

Add these costs together and compare the result with the price of a similar move-in-ready home. If the total cost is only slightly lower, the traditional home may offer better value because it involves less risk and fewer surprises.

Evaluate the Location

A damaged home in a strong location may be worth considering. A cheap home in an area with declining demand, limited employment, poor transportation, or difficult resale conditions may be a weaker investment.

Study nearby sales, rental demand, schools if relevant to the target buyer, crime information from reliable local sources, planned developments, flood risks, and neighborhood conditions. A renovation cannot easily fix a poor location.

Understand Your Time and Skill Level

Bank-owned homes may be suitable for buyers who have renovation experience, access to reliable contractors, or enough time to manage a project. They may be frustrating for buyers who need to move quickly or have limited experience estimating repair work.

Ask yourself:

  • Can I handle delays?
  • Do I have money available for unexpected repairs?
  • Can I manage contractors and permits?
  • Do I understand the inspection report?
  • Will I still be comfortable with the purchase if repairs cost more than expected?

If the answers are mostly no, a move-in-ready home may be a safer choice.


Steps to Take Before Making an Offer

Get Preapproved for Financing

A mortgage preapproval shows your estimated buying power and helps identify properties within your budget. It also allows your lender to review the property’s condition once you find a home.

If you plan to pay cash, keep enough funds available for repairs, taxes, insurance, and emergencies instead of using all your money on the purchase.

Work With an Experienced Professional

A real estate agent who has handled REO transactions can help explain bank addenda, offer procedures, deadlines, and required documents. A buyer’s agent may also help locate comparable sales and identify concerns in the listing.

Depending on the property and location, you may also need a home inspector, contractor, title company, real estate attorney, insurance agent, or environmental specialist.

Complete a Thorough Inspection

A general home inspection is a starting point, not a guarantee. Additional evaluations may be useful for the roof, foundation, sewer line, septic system, chimney, pests, mold, well, electrical system, or heating and cooling equipment.

Do not skip an inspection simply because the property looks attractive or the lender has already performed an evaluation. A bank’s valuation is usually designed to estimate market value, not provide a complete list of defects for the buyer.

Review the Contract Carefully

Bank-owned sellers may use their own purchase agreements and addenda. These documents may change inspection rights, closing dates, earnest money rules, possession terms, and the seller’s responsibilities.

Read the contract carefully and ask qualified professionals to explain language you do not understand. Pay close attention to deadlines because missing one may cause the offer to be canceled or the deposit to be at risk.

Calculate a Conservative Offer

Begin with the home’s likely market value in good condition. Subtract realistic repair costs, transaction expenses, holding costs, and a contingency reserve. The amount left should support your maximum offer.

This method is more reliable than choosing an offer based only on the bank’s asking price. The bank’s price may not reflect the property’s true condition or the cost of bringing it up to market standards.


Who Should Consider a Bank-Owned Foreclosure?

A bank-owned foreclosure may be worth considering for:

  • Buyers seeking a lower purchase price.
  • Investors who understand renovation and resale calculations.
  • Owner-occupants willing to complete repairs over time.
  • Buyers with strong financing or available cash reserves.
  • People who can tolerate delays and complicated paperwork.
  • Buyers who find a property in a desirable location with manageable defects.

It may not be suitable for:

  • Buyers with no emergency savings.
  • People who need a guaranteed move-in date.
  • Buyers uncomfortable with construction projects.
  • Anyone relying on a very tight monthly budget.
  • Buyers who cannot inspect the home properly.
  • People who are focused only on the advertised discount.

Are Bank-Owned Foreclosures Worth It?

Bank-owned foreclosures can be worth it, but they are not automatically good deals. The best opportunities usually combine a fair purchase price, a desirable location, manageable repairs, a clear title, and a buyer who has enough money and patience to complete the transaction properly.

The safest way to evaluate an REO property is to look beyond the asking price. Inspect the home, estimate repairs, review the title, compare recent sales, confirm financing, and keep a reserve for unexpected costs. If the total investment still makes financial sense after adding everything together, the property may be a worthwhile purchase.

In short, a bank-owned foreclosure is worth considering when the numbers work—not simply because the listing says “foreclosure.”

What Are Common Problems in Foreclosed Homes?

Buying a foreclosed home can sound like a dream come true—after all, who doesn’t love scoring a great deal? But before you start imagining yourself moving in or planning your renovation, it’s important to understand the other side of the coin. Foreclosed homes often come with hidden issues that could turn your bargain purchase into a money-draining project.

Let’s dive into the most common problems buyers run into with foreclosed properties, and how you can spot or prepare for them before making an offer.


1. Neglect and Lack of Maintenance

One of the biggest issues with foreclosed homes is neglect. When homeowners fall behind on their mortgage payments, they often also struggle to keep up with basic home maintenance.

From leaky roofs to broken HVAC systems, many foreclosed homes have gone a long time without proper care. Some common signs of neglect include:

  • Peeling paint or damaged siding.
  • Roof leaks or missing shingles.
  • Clogged gutters and poor drainage.
  • Malfunctioning HVAC or electrical systems.
  • Overgrown yards or dying landscaping.

In some cases, owners may even have started home improvements they couldn’t finish, leaving behind incomplete work or poor-quality repairs.

Tip: Always schedule a professional home inspection before purchasing. An inspector can uncover hidden issues like foundation cracks, structural damage, or mold behind walls that might not be visible at first glance.


2. Vandalism and Theft

Unfortunately, some foreclosed homes stay empty for weeks or even months. During that time, they can become targets for vandalism or theft.

It’s not uncommon to find:

  • Missing appliances, lighting fixtures, or HVAC units.
  • Stolen copper pipes or wiring (a favorite for scrap metal thieves).
  • Broken doors or smashed windows.
  • Graffiti or intentional destruction inside the property.

Former owners who were evicted under stressful circumstances may also damage the property before leaving. While not every foreclosure faces this issue, many do—especially those that have been on the market for a while.

Tip: When touring a foreclosed home, inspect utility systems carefully. Replacing stolen copper wiring or plumbing can add thousands to your repair bill.


3. Water Damage and Mold

Water damage is one of the most expensive problems lurking inside foreclosed homes. It can come from a variety of sources: burst pipes, leaky roofs, or even intentional flooding by frustrated former owners.

Water intrusion often leads to hidden mold, which can spread quickly and pose serious health risks. Some warning signs include:

  • Musty smells and discolored spots on walls or ceilings.
  • Peeling paint or warped flooring.
  • Water stains around windows, doors, or the basement.

If mold has spread behind walls or under flooring, remediation costs can skyrocket. In extreme cases, you might need to replace entire sections of drywall, insulation, and flooring.

Tip: If you see any signs of water intrusion, hire a mold inspector before closing the deal. Even small leaks can turn into major renovation headaches later on.


4. Pest Infestations

When a home sits vacant, pests can easily move in. Rodents, termites, cockroaches, and even birds find abandoned houses the perfect place to nest.

A pest problem can quickly lead to structural damage and hygiene issues. Look for these signs:

  • Droppings in corners, attics, or crawl spaces.
  • Chew marks on wiring or wood.
  • Wood powder near beams or walls (a sign of termites).
  • Buzzing, scratching, or chirping sounds from inside walls.

Addressing an infestation isn’t just about extermination—repairs may be needed for chewed wires, damaged insulation, or weakened wood supports.

Tip: Ask for a pest inspection alongside your general home inspection. It’s a small expense that could save you major repair costs later.


5. Broken or Outdated Systems

Utility systems—including electrical, plumbing, and HVAC—are crucial for any home’s comfort and safety. In foreclosed homes, these systems often break down due to non-use, sabotage, or neglect.

Here’s what you might find:

  • Outdated wiring that doesn’t meet current safety codes.
  • Leaky or rusted plumbing pipes.
  • Malfunctioning furnaces or air conditioners.
  • Damaged water heaters.

If the property was vacant through cold weather, frozen and burst pipes may have caused unseen water damage within walls or basements.

Tip: Turn on utilities during inspection if possible. It helps ensure everything works properly before you finalize the purchase.


6. Title and Legal Issues

While physical problems are common, legal complications can be just as tricky. Sometimes, foreclosed homes come with unresolved title issues that delay or derail a sale.

Common examples include:

  • Outstanding liens from unpaid taxes or homeowner association fees.
  • Former owners refusing to vacate.
  • Missing or incomplete documentation from the bank.

These issues could delay closing or even result in unexpected financial liability after purchase.

Tip: Work with a real estate agent or attorney experienced in foreclosures, and always purchase title insurance. It’s your best protection against legal surprises.


7. Outdated or Unsafe Structures

Some foreclosed homes haven’t been updated in decades. Beyond cosmetic issues, outdated structures can pose safety hazards.

You might find:

  • Asbestos in old insulation or tiles.
  • Lead-based paint in homes built before 1978.
  • Unpermitted additions or DIY renovations.
  • Weak foundation or unsafe decks.

Updating old homes to meet current safety codes often adds unexpected costs for new buyers.

Tip: Get estimates from a contractor before buying. That way, you’ll know how much you’ll really need to spend to bring the house up to standard.


8. Unpleasant Odors and Stains

Vacant homes often develop unpleasant smells. Whether it’s pet odors, cigarette smoke, mold, or even stale air, bad smells can stick to carpets, walls, and vents.

In more severe cases, you might encounter stained carpets, smoke residue, or water-damaged walls—all of which require deep cleaning or replacement.

Tip: While some odors can be removed with professional cleaning, others may require replacing flooring, repainting, or even treating ductwork. Don’t underestimate how persistent odor issues can be.


9. Exterior and Curb Appeal Issues

Curb appeal is often the first casualty in foreclosures. Overgrown lawns, peeling paint, broken fences, or damaged driveways can make a home look worse than it really is.

Although these are mostly cosmetic problems, they still cost time and money to fix. Plus, neglected landscaping can hide more serious issues like soil erosion or grading problems that cause water to pool near the foundation.

Tip: Rehabilitating a home’s exterior improves not only its appearance but also its long-term value. A little landscaping can go a long way toward restoring charm.


10. Unseen Structural Damage

Some of the worst problems in foreclosed homes are the ones you can’t see right away. Structural issues are particularly concerning because they affect the home’s safety and integrity.

Potential hidden problems include:

  • Foundation cracks or settling.
  • Issues with load-bearing walls or beams.
  • Rotting floor joists.
  • Significant termite damage.

Repairing structural damage can quickly become expensive and may require permits or specialized contractors.

Tip: Don’t skip the structural inspection. Even if a home looks fine on the surface, stress cracks or uneven floors may hint at deeper problems.


11. Hidden Costs After Purchase

Even after you’ve dealt with visible repairs, hidden costs can still surface. For instance:

  • Reconnecting utilities may have fees.
  • Local code violations might require fixes before move-in.
  • Property taxes and HOA fees could be higher than expected.
  • Insurance may cost more due to the property’s condition.

A foreclosed home might seem like a great deal upfront, but these extra costs can shrink your savings fast.

Tip: Budget an additional 10–15% of the purchase price for unforeseen repairs and fees. It’s better to overestimate than be caught off guard.


12. Emotional and Time Commitment

Many buyers don’t anticipate how emotionally and physically exhausting buying a foreclosed property can be. Between negotiating with banks, waiting for approvals, dealing with repairs, and handling paperwork, the process can take months.

Restoring a neglected home requires patience and commitment—not just money.

Tip: If your goal is to move in quickly, a foreclosure might not be the right fit. But if you’re up for a project and see potential in bringing a property back to life, it could be a rewarding challenge.


13. Tips to Protect Yourself When Buying a Foreclosure

To safeguard your investment, consider these best practices:

  1. Get a thorough inspection. Don’t skip any step, from structural to pest and mold checks.
  2. Work with professionals. An experienced agent, inspector, and lawyer can help you navigate the process safely.
  3. Research the property’s history. Check for liens, unpaid taxes, or known damage reports.
  4. Budget for extra repairs. Build a contingency fund. Unexpected issues will likely come up.
  5. Act quickly but wisely. Foreclosures can attract multiple buyers—stay informed and realistic about your limits.

Buying a Foreclosed Home

Buying a foreclosed home can be both exciting and risky. The potential for savings makes them attractive, but hidden problems can turn those savings into expenses if you’re not careful.

Most of the issues—neglect, water damage, theft, pests, or maintenance—can be resolved with the right planning and budget. The key is to approach the process with open eyes, do proper due diligence, and have a professional team by your side.

When handled smartly, turning a troubled foreclosure into a cozy home can be one of the most satisfying real estate moves you’ll ever make.


Would you like me to make this post more SEO-optimized with headings and meta descriptions for your blog platform?

Add to follow-up

Check sources

How Much Do Banks Sell Foreclosures For?

Banks sell foreclosures for a price that is usually lower than the market value of similar homes. You might be wondering how much lower and what factors decide the final price. The answer is not always the same, but there are clear patterns that help you understand what to expect.


How Banks Decide the Price of Foreclosures

Banks do not just pick a random number when pricing foreclosed homes. They hire real estate agents to assess the property and estimate its value in its current condition. The agents look at what the home is worth as-is, what it could be worth after repairs, and how much those repairs would cost. The bank then uses this information to decide if it is better to sell the home quickly as-is or to invest in repairs for a higher price later.

The bank’s main goal is to recover as much of their losses as possible. The original mortgage amount owed by the homeowner is rarely a big factor in the final price. Instead, the bank focuses on what will help them get the property sold and recoup their costs. Sometimes, if the bank makes more than enough to cover their expenses, the extra money might even go back to the original owner, but this is rare and depends on local laws.


What Makes Foreclosure Prices Lower

Foreclosed homes are usually sold at a discount compared to regular homes. On average, the discount can be around 7% to 10% below market value, but this can vary widely depending on the area and the condition of the home. The reason for the lower price is simple: banks want to sell these properties quickly. They do not want to hold onto them for long, so they often price them to attract buyers fast.

Another reason for the lower price is that foreclosed homes are often sold “as-is.” This means the bank will not make repairs or upgrades before selling. Buyers need to be ready to handle any repairs or issues themselves. The condition of the home can have a big impact on the final price. If the home needs a lot of work, the price will be lower to reflect that.


Factors That Affect the Final Price

Several things can change how much a bank will sell a foreclosure for. The local real estate market is one of the biggest factors. In a hot market, banks might be able to sell foreclosures for closer to market value. In a slow market, they might need to lower the price more to attract buyers.

The condition of the home is another major factor. Homes that are in good shape or need only minor repairs will sell for higher prices. Homes that need a lot of work will be priced lower. The location also matters. Homes in desirable neighborhoods or cities will usually sell for more, even if they are foreclosures.

Banks also look at feedback from buyers and agents. If a home is not getting much interest, the bank might lower the price to make it more attractive. If buyers are interested but not making offers, the bank might decide to fix up the home or lower the price to close the deal.


What You Can Expect When Buying a Foreclosure

If you are thinking about buying a foreclosure, you should know that prices can vary a lot. In some areas, you might find homes selling for 10% to 20% below market value. In other areas, the discount might be smaller, especially if the market is strong or the home is in good condition.

It is also important to remember that buying a foreclosure can come with extra costs. You might need to pay for repairs, inspections, and closing costs. Some banks require a larger down payment or have stricter lending requirements for foreclosed homes.


Real-World Examples and Trends

In 2025, foreclosure activity has been on the rise in some parts of the country, but overall rates are still low compared to historical highs. States like Florida, Nevada, and South Carolina have some of the highest foreclosure rates, which means there are more foreclosed homes available for sale in these areas. The average time it takes to complete a foreclosure has also decreased, meaning banks are selling these homes faster than before.

Here is a quick look at some recent foreclosure data:

StateForeclosure Rate (1 in X)REO Count Q3 2025
Florida814762
Nevada8311574
South Carolina8672769
Illinois9445764
Delaware974470
Texas112310584
California129711207
New York16215269

This table shows that some states have more foreclosed homes available than others, which can affect prices and competition.


Tips for Getting the Best Deal

If you want to get the best price on a foreclosure, it helps to do your homework. Look at recent sales of similar homes in the area to get an idea of what the market value is. Check the condition of the home and estimate how much repairs might cost. Talk to a real estate agent who has experience with foreclosures to help you understand the process and negotiate the best price.

Banks are usually willing to lower the price if a home is not selling quickly. If you see a foreclosure that has been on the market for a few months, it might be a good time to make an offer. Just be ready to act fast, because foreclosures can sell quickly when the price is right.


Final Thoughts

Banks sell foreclosures for less than market value to recover their losses and sell the homes quickly. The exact price depends on the local market, the condition of the home, and how much competition there is. If you are looking for a good deal, foreclosures can be a great option, but it is important to do your research and be ready for any extra costs or repairs.

Who Manages REO Properties for Banks?

If you’ve heard the term REO and wondered who manages these properties for banks, you’re in the right place. REO stands for Real Estate Owned, and it means the property is owned by a bank or lender after a foreclosure. But who takes care of these homes once they belong to the bank? Let’s break down exactly who manages REO properties and how they do it.


What Are REO Properties and Why Do Banks Manage Them?

When a homeowner can’t keep up with mortgage payments, the bank may start foreclosure proceedings. If the home doesn’t sell at the foreclosure auction, it returns to the bank’s ownership and becomes an REO property. Banks don’t want to hold on to these homes for long. They want to sell them quickly to recover money. That’s why banks appoint professionals to manage REO properties for them.

Managing REO properties involves a lot: making sure the property stays in good condition, keeping it secure, handling paperwork, and preparing it for sale. This process requires specialized knowledge and contacts, so banks usually don’t manage these properties themselves. Instead, they hire experts to do it for them.


Who Exactly Manages REO Properties for Banks?

Banks rely on several types of professionals and companies to manage their REO properties. Here’s a quick look at the main players responsible for this job:

  • REO Management Companies: These are specialized companies that handle the day-to-day management of REO properties for banks. They take care of everything from inspections and repairs to property maintenance and marketing. They act as the bank’s representative on the ground.
  • Property Management Firms: Some banks use general property management firms experienced in managing foreclosed properties. These firms deal with upkeep, tenant relations (if rented), and ensuring the property meets safety standards.
  • REO Asset Managers: These are professionals or teams within banks who oversee REO portfolios. They coordinate between various service providers like management companies, real estate agents, and contractors to ensure properties are managed efficiently.
  • Real Estate Agents Specialized in REO Sales: While primarily focused on selling, these agents often coordinate with management teams to stage properties, schedule showings, and negotiate deals.
  • Contractors and Inspectors: Though not managers, these professionals support REO management by repairing damages, conducting inspections, and helping make properties sale-ready.

How Do REO Management Companies Work?

When banks hire REO management companies, they hand over responsibility for the physical and administrative care of these homes. Here’s what these companies typically do for banks:

  • Inspect and Secure: Right after a property becomes REO, it needs inspection. The management company checks its condition and secures it against vandalism or theft.
  • Maintain and Repair: They coordinate routine maintenance, landscaping, and emergency repairs to keep the property attractive and safe.
  • Property Marketing: REO managers often help list the property for sale, ensuring photos, descriptions, and information are accurate.
  • Handle Paperwork: Banks want a smooth closing process, so management teams make sure all legal and financial documentation is handled correctly.
  • Coordinate with Agents: They work closely with real estate agents to prepare the property for showings and help close sales quickly.

Because banks want to avoid losses, these companies work to minimize holding time and expenses. Their efficiency benefits both the bank and future buyers like you.


Why Don’t Banks Manage REO Properties Themselves?

Managing properties isn’t a bank’s main job. Their expertise lies in lending money and handling finances, not day-to-day property upkeep or sales. Managing an REO portfolio requires:

  • Knowledge of property maintenance and repair
  • Relationship with reliable contractors
  • Handling extensive paperwork and legal requirements
  • Marketing skills to sell homes quickly

Hiring professionals lets banks focus on banking and leaves the detailed work to experts.


What Should You Know if You’re Buying an REO Property?

If you’re interested in buying a bank-owned REO home, understanding how these properties are managed helps you deal with the right people. Usually, you’ll be working with:

  • The real estate agent representing the bank
  • The REO management company handling the property
  • Sometimes the bank’s asset manager answering higher-level questions

Knowing the roles helps you communicate effectively and speeds up the buying process. REO homes might require repairs or updates, so expect the management team to provide accurate information about the condition of the property.


So Who Manages REO Properties for Banks?

REO properties are managed primarily by specialized REO management companies and property management firms hired by banks. These companies inspect, maintain, repair, and market the homes until they sell. Banks themselves oversee these processes through REO asset managers but rely heavily on outside experts to handle the work. If you plan to buy an REO home, you will interact mostly with the management companies and real estate agents assigned by the bank. This setup ensures the property is cared for and sold efficiently.

Now you know who takes care of REO properties for banks and why specialized management is key to these homes’ smooth handling. If you’re on the market for an REO property, working with these professionals will help you make the best decision.

Are REO Properties Good Investments?

If you’re curious about REO properties and whether they make good investments, you’ve come to the right place. REO stands for “Real Estate Owned,” and these properties are ones banks or lenders have taken back after a foreclosure. But before jumping in, you’ll want to understand what makes them unique and how they can fit your investment goals. Let’s break it all down for you.

What Are REO Properties and Why Do They Exist?

REO properties end up back in the hands of banks because the previous homeowners couldn’t keep up with mortgage payments. When a home goes through foreclosure, the bank tries to sell it at auction. If no one buys it, the property becomes “Real Estate Owned” by the lender.

You might find these homes listed at prices below market value, which is what often attracts investors. However, keep in mind that banks just want to recoup their losses quickly and move on, so they may not put much effort into upgrades or repairs before selling.

Pros of Investing in REO Properties

You may wonder whether REO properties provide a good investment opportunity. Here are some benefits you might find appealing:

  1. Lower Purchase Price: Because banks want to sell these properties fast, prices often come discounted compared to regular homes on the market. This could mean a chance to buy low and build equity quickly.
  2. Clear Title: One major advantage is that banks usually clear any liens or debts before selling. This saves you paperwork headaches and helps ensure a clean title.
  3. Negotiation Room: Since banks are motivated sellers, you might have space to negotiate price or terms, especially if the home has been sitting unsold for some time.
  4. Potential for Profit: If you buy wisely, you could renovate and sell for a profit or rent the property out for steady income.

The Challenges You Should Know About

While REO properties sound like a bargain, you need to watch out for potential risks before you invest:

  1. Property Condition: Banks rarely fix these homes up. You might face costly repairs, from minor cosmetic issues to bigger problems like foundation damage or outdated systems.
  2. Competition from Other Investors: Many buyers watch for REOs, so you may end up in bidding wars or face tight deadlines to decide.
  3. Limited Disclosures: Unlike traditional sales, banks often sell REOs “as-is,” meaning you get little information about the property’s issues upfront.
  4. Potential Holding Costs: If repairs take longer, you’ll keep paying property taxes, insurance, and utilities, squeezing your profit margin.

How to Decide if an REO Property Is Right for You

You might be excited about REO investments, but to avoid surprises, try following these steps:

  • Do Your Homework: Research the local market, property history, and neighborhood conditions.
  • Get a Home Inspection: Even if banks sell as-is, it’s wise to pay for an inspection so you know what to expect.
  • Calculate Repairs and Costs: Estimate renovation expenses realistically—not everyone can fix a major repair cheaply or quickly.
  • Have Financing Ready: Some lenders may not approve loans for homes that need extensive repairs, so keep your financing options clear.
  • Plan Your Investment Strategy: Are you flipping, renting, or holding long-term? Your strategy will shape which properties you choose.

So Are They Really Good Investments?

The short answer is yes, but only if you go in with your eyes open. They can offer attractive prices and profit potential if you know how to pick the right home, account for repairs, and stay patient.

If you enjoy hands-on projects, like renovating properties yourself, you might find REOs especially rewarding. On the other hand, if you want a move-in ready home or can’t handle unexpected repair costs, you might want to look elsewhere.

In the end, investing in REO properties can be a solid choice, but it requires careful research, smart budgeting, and a bit of risk appetite from you. If you’re ready to embrace those, this market could be a great way to grow your real estate portfolio.

How to Become a REO Agent for Banks: Your Complete Guide

If you’ve ever wanted to break into a real estate niche where you get to work side-by-side with banks, manage unique properties, and master new processes, becoming a REO (Real Estate Owned) agent could be the perfect path for you. Today you’ll discover in easy steps how to become a REO agent for banks and get those in-demand listings.

What Is a REO Agent and What Do You Actually Do?

REO agents are licensed real estate professionals who handle the sale of properties owned by banks and financial institutions due to foreclosure or failed auctions. You step in after a home hasn’t sold at auction, helping banks manage, market, and sell it to a new owner. As a REO agent, you’ll:

  • Prep and manage vital paperwork between the bank, buyers, contractors, and vendors
  • Represent the bank in negotiations, buyer meetings, and sometimes even property closings
  • Arrange, oversee, or perform inspections, appraisals, property maintenance, and repairs
  • Organize bids from contractors and manage property preservation
  • Prepare key documents such as BPOs (Broker Price Opinions), which help assess home value for the bank
  • Juggle deadlines, follow industry rules, update listings, and coordinate a wide cast of stakeholders

You’ll need to be attentive, persistent, organized, and ready to handle a bit more complexity than the typical residential agent—but you’ll also find yourself with a solid career that’s always in demand, especially when foreclosure rates increase.

Step 1: Lay the Educational Foundation

You can’t become a REO agent without the basics. Every successful REO agent starts with the same core requirements:

  1. Finish high school or equivalent education
  2. Consider attending college (optional)—Studying business, finance, or real estate can give you an advantage but isn’t strictly necessary
  3. Complete pre-licensing coursework for your state—Every state has unique education requirements for real estate licensing
  4. Pass your real estate exam and get licensed in your state

Most banks and asset management companies won’t even look at an agent who isn’t fully licensed, so this part simply can’t be skipped.

Quick Licensing Tips

  • Research your state’s licensing board to find their specific exam prep, age, background check, and continuing education requirements
  • Remember, many successful REO agents also take business classes or earn a related degree to stand out from the crowd

Step 2: Get Real-World Experience and Build Your Track Record

You won’t snag bank clients as a brand-new agent. Banks and asset management companies prefer working with experienced agents who know how to close deals and solve problems. Here’s how you can build your reputation:

  • Start as a traditional real estate agent. Join a brokerage and learn everything about property sales, marketing, negotiations, and closing deals
  • Work for agencies already handling REO listings. This gives you insider experience and a pipeline to future opportunities
  • Help buyers purchase REO and HUD homes. Even if you don’t have your own bank listings yet, being involved in these deals boosts your credibility
  • Offer BPO services. By performing Broker Price Opinions for asset managers, you’ll gain direct bank experience, get on vendors’ radar, and learn valuation intricacies

Focus on building skills in communication, negotiation, organization, and property valuation—these are your bread and butter as a REO agent.

Step 3: Register With REO Networks and Asset Management Platforms

You’ll need to work through a whole web of networks, asset management platforms, and government programs if you want to become a go-to REO agent. Here’s what you do:

  • Join REO directories and platforms like REONetwork.com, as asset managers search these networks to fill assignments
  • Register with asset management companies who handle bulk property portfolios for the nation’s biggest banks
  • Sign up with platforms used by banks like Equator and RES.NET—these are used to list, assign, and track properties for sale
  • Get approved to list government-owned REO properties by signing up for programs with Fannie Mae, Freddie Mac, and HUD

Most platforms and companies will want your resume, proof of licensing, experience history, and references from past REO deals or BPOs. Start collating these documents into a “REO packet” you can reuse for various applications.

Step 4: Gain REO-Specific Certifications and Expand Your Skills

You want to show asset managers and banks that you’re not just a standard agent—you know your stuff. Earning extra certifications proves your dedication and knowledge:

  • Consider the Certified Distressed Property Expert (CDPE) designation
  • Enroll in National Association of Realtors (NAR) certifications for short sales, foreclosures, or property preservation
  • Complete REO and BPO training courses that teach you how to create BPOs, manage distressed properties, and navigate the unique sales process

Certifications and continuing education provide an instant boost to your credibility and help you stay current with REO trends.

Step 5: Master Relationship Building and Marketing

REO listings are all about connections—you’ll need to network constantly, stay top of mind, and prove yourself with every opportunity to earn more listings. Here are key strategies:

  • Develop relationships with local and national asset managers—a friendly, reliable agent is often preferred over an unknown name
  • Market yourself as a REO specialist using a website, targeted emails, and well-crafted presentations for banks and managers
  • Stay persistent and follow up regularly with decision-makers
  • Offer value with competitive pricing, turnkey property management services, and excellent response times—banks want fast, seamless deals

Customize your pitch for each bank or asset manager you approach, highlighting your experience, results, and unique value proposition. Prepare a “script” that tells your story and showcases your specialized skills.

Step 6: Understand Key REO Agent Duties and Expectations

Banks expect their REO agents to deliver professional results under tight deadlines, and they have very specific processes for everything. You’ll need to:

  • Complete Broker Price Opinions (BPOs) promptly and accurately—you assess local comparable sales, current listings, and market conditions for the property
  • Coordinate repairs, maintenance, cash-for-keys, and even evictions—sometimes you’ll organize offers for occupants to leave, other times you’ll help with formal evictions
  • Market and list properties in the Multiple Listing Service (MLS) quickly
  • Communicate constantly with the bank, asset manager, contractors, and other stakeholders
  • Submit all offers, documentation, and update records within strict timeframes
  • Handle multiple offers, negotiations, and facilitate a smooth closing process
  • Maintain compliance with fair housing and foreclosure laws at every step

Step 7: Secure Your First Listings and Deliver Results

Once you’re set up with the right credentials, experience, and platforms, you’re ready to start targeting REO listings. You’ll want to:

  • Reach out to banks directly, introduce yourself, and follow up persistently
  • Target smaller community banks or credit unions at first—they may be more willing to give new REO agents a shot
  • Offer to handle BPOs or open houses to get your foot in the door
  • Join industry groups, attend foreclosure auctions, and connect with attorneys handling bank-owned real estate
  • Be ready with your REO packet and references whenever you apply or submit a pitch

Once you land your first assignment, always deliver on promises and keep a proactive line of communication open. The better your results, the more banks and asset managers will want to work with you again and again.

Common Questions When Becoming a REO Agent

Do banks require a certain amount of experience?

Yes, most want to see that you’ve closed deals, handled distressed properties, or provided high-quality BPOs for other REOs or HUD properties before assigning listings to you.

Do I need special insurance?

You’ll need Errors & Omissions (E&O) insurance, just like your traditional real estate business, but make sure your coverage extends to all REO activities.

Can new agents break into REOs, or is it too competitive?

It’s competitive, but not impossible. Work for brokerages with existing REO business, assist on transactions, or perform BPOs for practice and to show you can deliver. Persistence pays off here because agencies and banks sometimes need fresh agents as experienced ones move to other roles or retire.

Do you have to manage property repairs and evictions?

You’ll often coordinate everything from repairs to “cash for keys” offers and even evictions. Learn the processes and build a Rolodex of reliable vendors to help you manage these special cases smoothly.

Your Path to Becoming a REO Agent for Banks

You now know exactly how to become a REO agent for banks. Start with your license, build your experience, connect to the right networks, and always keep learning new skills. Prioritize relationships, follow the steps above, and you’ll soon be the top candidate for bank-owned listings in your area. Keep your paperwork meticulous, your attitude positive, and your follow-up persistent—and watch your REO business grow as your expertise grows.

If you’re ready for a real estate niche that’s challenging, profitable, and truly different, jump in. You’ve got what it takes to start your career as a REO agent for banks today

Can You Negotiate with a Bank-Owned Property?

If you’re considering buying a bank-owned property—often called an REO (Real Estate Owned) home—you’re probably wondering: Can you actually negotiate with the bank? The answer is yes, you absolutely can! But the process is different from negotiating with a traditional seller, and knowing how to approach it can make all the difference in getting a great deal. Let’s break down everything you need to know to confidently negotiate and buy a bank-owned property.


Understanding Bank-Owned Properties

First, let’s clarify what a bank-owned property is. When a homeowner defaults on their mortgage and the property fails to sell at auction, it becomes “Real Estate Owned” by the bank or lender. Banks aren’t in the business of holding onto homes—they want to sell these properties as efficiently as possible. This motivation can work in your favor, but banks are also systematic and business-minded sellers. They want to recoup as much of their investment as possible and will stick to a process that’s quite different from dealing with an individual homeowner.


Can You Negotiate the Price on a Bank-Owned Property?

Yes, you can negotiate the price on a bank-owned property. In fact, banks almost never accept the first offer they receive. They expect negotiation and often set the initial price based on market analysis and the condition of the property. Here’s what you need to know about the negotiation process:

  • Banks review all offers carefully and rarely accept the first one outright. They often invite “highest and best” offers, which can lead to a bidding war if the property is in demand.
  • Negotiations typically involve counteroffers. The bank may respond to your initial offer with a counter, and you’ll have the opportunity to adjust your bid or terms.
  • Banks are motivated but not desperate. They want to sell, but they also have a process to ensure they get a fair price. If a property has been on the market for a while, you may have more room to negotiate.

How to Prepare for Negotiation

Negotiating with a bank is different from negotiating with a homeowner. Banks don’t have emotional attachments to the property, but they do have strict procedures and multiple decision-makers involved. Here’s how you can set yourself up for success:

1. Do Your Homework

  • Research comparable sales in the area so you know what similar homes are selling for. This gives you a solid foundation for your offer and negotiation.
  • Get an appraisal and inspection. An appraisal helps you determine if the asking price is fair, while an inspection reveals any issues that could justify a lower offer.
  • Understand the property’s history. Has it been vacant for a while? Are there repairs or liens? Knowing these details helps you negotiate from a position of strength.

2. Get Your Finances in Order

  • Have proof of funds or pre-approval ready. Banks want to know you’re a serious buyer who can close the deal. Include a recent bank statement (with sensitive info blacked out) or a pre-approval letter with your offer.
  • Be prepared to put down a substantial deposit. A deposit of 10% or more shows the bank you’re committed and can make your offer stand out from others.

3. Work with an Experienced Agent

  • Hire a real estate agent who knows REO properties. The process can be complex, and an experienced agent can guide you through the paperwork, negotiation, and closing.

The Negotiation Process: Step-by-Step

Let’s walk through what you can expect when negotiating for a bank-owned property:

Step 1: Make an Offer

  • Submit your offer through the bank’s broker or listing agent. Banks usually work with a broker who acts as the gatekeeper for all offers.
  • Include all required documentation. This means your proof of funds, pre-approval letter, and any special forms the bank requires.
  • Consider making your offer contingent on inspection. This protects you if the inspection uncovers major issues.

Step 2: Wait for the Bank’s Response

  • Be patient—banks take longer to respond. Because multiple people or departments often review offers, it may take days or even weeks to hear back.
  • Expect a counteroffer. Banks rarely accept the first offer. They may counter with a higher price or different terms.
  • Respond quickly. Once the bank responds, they’ll expect you to act fast to keep the process moving.

Step 3: Negotiate Terms

  • Negotiate not just on price, but also on closing timeline, contingencies, and repairs. Banks prefer quick closings—offering to close in 30 days or less can make your offer more attractive.
  • If the inspection reveals issues, use this to negotiate. Document needed repairs and request a price reduction or credit.
  • Be flexible but firm. Know your limits and stick to your budget, but be ready to adjust your offer if the bank counters.

Step 4: Finalize the Deal

  • Once you reach an agreement, finalize your financing and verify the property’s title. Banks usually clear the title before selling, but it’s wise to double-check.
  • Complete all paperwork and prepare for closing. Review all documents carefully, especially any bank-required addendums.

Tips for Successful Negotiation

Here are some practical tips to help you negotiate effectively with a bank:

  • Start with a reasonable offer. If you lowball too much, the bank may ignore your offer. Use your research to justify your price.
  • Offer a larger deposit. A deposit of at least 10% shows you’re serious and can help your offer stand out.
  • Offer a quick closing. Banks want to get these properties off their books. If you can close in 30 days or less, you have an advantage.
  • Waive unnecessary contingencies. If you’re confident in the property’s condition, waiving inspection or financing contingencies can make your offer more appealing—but only do this if you’re sure.
  • Be prepared for delays. Even if you offer a quick closing, banks may take longer to process paperwork and clear the title.
  • Stay professional and persistent. Banks are used to buyers backing out. Show you’re committed and ready to close.

Common Questions About Negotiating Bank-Owned Properties

Can I ask the bank to make repairs?

Banks usually sell properties “as-is” and rarely agree to make repairs. However, if the inspection uncovers major issues, you can use this information to negotiate a lower price or request a credit at closing.

Will the bank pay closing costs?

Sometimes banks are willing to cover some closing costs, especially if it helps close the deal. It doesn’t hurt to ask, but don’t make this a dealbreaker if they decline.

Is there room for negotiation if there are multiple offers?

If the property is in high demand, the bank may ask for “highest and best” offers from all interested buyers. In this case, you’ll need to put your best foot forward and may have less room to negotiate.

What if my offer is rejected?

Don’t be discouraged. You can submit a new offer or look for other properties. Sometimes, if a deal falls through with another buyer, the bank may come back to you.


So Can You Negotiate?

Negotiating for a bank-owned property is absolutely possible and even expected. The key is to approach the process like a business transaction—do your research, be prepared with your finances, and work with professionals who understand the REO process. Banks want to sell, but they want to do so on their terms, so patience and persistence are essential.

If you’re ready to make an offer on a bank-owned property, remember:

  • Do your due diligence.
  • Have your finances ready.
  • Negotiate confidently, but be realistic.
  • Work with experts who know the process.

With the right approach, you can successfully negotiate and buy a bank-owned property—sometimes at a significant discount—while avoiding common pitfalls along the way. Happy house hunting!

Are REO Properties a Good Deal? Everything You Need to Know Before You Buy

If you’re searching for a bargain in real estate, you’ve probably stumbled across the term “REO property.” You might be wondering: Are REO properties a good deal, or are they just a headache in disguise? Let’s break down what REO properties are, the pros and cons, and whether you should consider snapping one up for your next home or investment.


What Are REO Properties?

REO stands for “Real Estate Owned,” and it refers to properties that have gone through the foreclosure process and are now owned by a lender—usually a bank. These homes didn’t sell at auction, so the bank is left holding the keys and is eager to get them off their books. You’ll often see REO properties listed as “bank-owned” homes.

Banks aren’t in the business of being landlords or homeowners. They want to recover their losses quickly, so they often price REO properties below market value to encourage a fast sale. This creates an opportunity for buyers looking for a deal.


Why REO Properties Can Be a Good Deal

Discounted Prices

The biggest draw of REO properties is the price. Banks are usually motivated sellers, and they often list these homes at a discount compared to similar properties in the area. If you’re hunting for a bargain, REOs are worth a look.

No Outstanding Liens or Taxes

One of the headaches of buying a foreclosure can be dealing with unpaid property taxes or other liens. With REO properties, the bank typically clears all outstanding debts, so you get a clean title and don’t inherit someone else’s bills.

Negotiation Power

Because banks want to sell quickly, you often have more room to negotiate on price or terms than with a traditional seller. If you’re prepared, you might be able to score an even better deal.

Potential for High Return on Investment

For investors, REO properties can be a goldmine. You can buy at a discount, rehab the property, and either flip it for a profit or rent it out for steady income. If you have the skills (or the right team), the numbers can work in your favor.


Risks and Challenges of Buying REO Properties

Sold As-Is

REO properties are almost always sold “as is.” The bank isn’t going to make repairs or spruce up the place before handing over the keys. Many REO homes have been neglected, and some may need major repairs to be livable. You’ll want to budget for renovations and get a thorough home inspection before committing.

Potential for High Repair Costs

Because previous owners may have struggled financially, maintenance is often deferred. Some REO properties need only cosmetic fixes, but others can require tens of thousands of dollars in repairs. Always factor in these costs when calculating whether you’re getting a true deal.

Limited Disclosures

Banks don’t have to disclose much about the property’s condition. Unlike a traditional seller, they probably haven’t lived in the home and may not know about hidden issues. This makes inspections and due diligence extra important.

Possible Occupancy Issues

If the property is a multi-family home or rental, there may still be tenants living there. You could become a landlord overnight, whether you want to or not, and you’ll need to follow local laws about tenant rights and leases. Make sure you understand what you’re getting into.

Competitive Market

Everyone loves a bargain, so REO properties can attract multiple offers, especially in hot markets. You’ll need to act quickly and have your financing lined up to compete with other buyers.

Complex Buying Process

Purchasing an REO isn’t always as straightforward as a regular home sale. Banks have their own processes and paperwork, and contracts are often written in their favor. It’s smart to hire a real estate agent experienced with REOs and consider consulting a lawyer to review the contract.


How to Decide if an REO Property Is Right for You

Do Your Homework

Before making an offer, research the property thoroughly. Get a professional inspection and appraisal, and check the title to make sure there are no surprises. If you’re not comfortable with the potential risks, it might not be the right deal for you.

Calculate the True Cost

Don’t just look at the sticker price. Add up the cost of repairs, closing costs, and any other expenses. Compare this total to the market value of similar homes in the area to see if you’re really getting a bargain.

Have Your Financing Ready

Banks want to close quickly and won’t wait around for you to get your finances in order. Have your pre-approval letter or proof of funds ready so you can move fast.

Know Your Exit Strategy

If you’re buying as an investment, have a clear plan for how you’ll make money on the property—whether that’s flipping, renting, or holding for appreciation. If you’re buying as a primary residence, make sure you’re comfortable living through any needed renovations.


Are REO Properties a Good Deal? The Bottom Line

REO properties can absolutely be a good deal, but they’re not for everyone. If you’re looking for a move-in-ready home with minimal hassle, an REO might not be the best fit. But if you’re willing to roll up your sleeves, do your homework, and take on some risk, you can score a property below market value and potentially build significant equity.

You’ll need to be prepared for the challenges—especially repairs, limited disclosures, and a sometimes-complicated buying process. But with careful planning and the right team, you can turn an REO property into a great investment or a home that’s truly your own.

In summary: REO properties are a good deal for buyers who are prepared, resourceful, and willing to take on a project. They’re not a shortcut to easy riches, but with the right approach, they can offer real value and opportunity.


Quick Tips for Buying REO Properties

  • Always get a professional inspection and appraisal.
  • Hire an experienced real estate agent and consider a lawyer.
  • Have your financing ready before you make an offer.
  • Budget for repairs and unexpected costs.
  • Do your research on the neighborhood and comparable sales.
  • Be ready to act fast in a competitive market.

If you’re up for the challenge, an REO property could be your ticket to a great deal in real estate. Happy house hunting!

Can You Wholesale REO Properties?

Everything You Need to Know About Wholesaling Bank-Owned Homes

If you’re interested in real estate wholesaling, you’ve probably heard about REO properties and wondered if you can wholesale them. The short answer is yes, you can wholesale REO (Real Estate Owned) properties, but the process comes with unique challenges and rules compared to wholesaling privately owned homes. In this guide, you’ll discover exactly how wholesaling REO properties works, what you need to watch out for, and how to set yourself up for success.


What Are REO Properties and Why Are They Wholesale Targets?

REO properties are homes that have gone through the foreclosure process and are now owned by a bank or lender. Banks are often motivated to sell these properties quickly, sometimes at prices below market value, making them attractive opportunities for investors and wholesalers.

You can think of REOs as “distressed” properties, but instead of dealing with individual homeowners, you’re negotiating with institutions. This changes the game, but it doesn’t mean you can’t play. In fact, many wholesalers specifically target REOs because banks want these properties off their books, and that urgency can lead to deals with strong profit potential.


Can You Legally Wholesale REO Properties?

Yes, you can wholesale REO properties, but you need to understand the legal and practical differences compared to wholesaling traditional homes. Wholesaling, in general, is legal in most states, but the specifics—especially with REOs—depend on your location and the bank’s requirements.

Here’s what you need to keep in mind:

  • Assignment Clauses: Many banks that own REOs use contracts that prohibit assignment. This means you can’t simply assign your purchase contract to another buyer, which is the classic wholesaling method.
  • Double Closing: If assignment isn’t allowed, you may need to use a double closing (buying and immediately reselling the property) or an entity assignment (selling the LLC that holds the contract).
  • Licensing: Some states require you to have a real estate license to wholesale properties, especially if you’re doing multiple transactions or marketing the property publicly.
  • Disclosure: Full transparency is required. You must clearly disclose your intentions to all parties, especially if you’re not the end buyer.

How Does Wholesaling an REO Property Work?

Wholesaling REOs follows the same basic principles as traditional wholesaling, but there are a few extra hoops to jump through. Here’s a step-by-step breakdown of how you can wholesale an REO property:

1. Build Your Buyers List

Before you even start looking for REOs, develop a list of cash buyers—usually investors—who are interested in distressed properties. Knowing what your buyers want helps you target the right deals and move quickly when you find one.

2. Find REO Properties

You can find REO properties through:

  • MLS (Multiple Listing Service)
  • Bank and lender websites
  • Online auction sites
  • Local real estate agents who specialize in REOs
  • Public records and foreclosure lists

Look for properties that have been on the market for a while or need repairs. These are more likely to be discounted and attractive to your buyers.

3. Analyze the Deal

Do your homework! Calculate the after-repair value (ARV) of the property, estimate repair costs, and determine your maximum allowable offer (MAO). Remember, your buyer will want to pay no more than 70% of the ARV minus repairs and your fee.

4. Make an Offer and Get the Property Under Contract

When you make an offer on an REO, be prepared to show proof of funds and possibly put down a larger deposit than you would with a private seller. Banks want to see that you’re serious and capable of closing the deal.

Tips for getting your offer accepted:

  • Offer a larger deposit (10% is often recommended).
  • Waive inspections if you’re confident about the property’s condition (this can make your offer more attractive to the bank).
  • Be ready to move quickly—banks don’t want to wait.

5. Understand the Contract Terms

Carefully review the bank’s contract. Many REO contracts do not allow assignment, so you’ll need to plan for a double closing or entity assignment if you can’t assign the contract directly.

  • Double Closing: You buy the property from the bank and immediately resell it to your end buyer, often on the same day. This requires you to have access to funds or transactional funding.
  • Entity Assignment: You form an LLC, put the property under contract in the LLC’s name, and then sell the LLC to your buyer.

6. Find Your End Buyer

Once you have the property under contract, market it to your buyers list. Since you’re dealing with REOs, your buyers will usually be investors looking for fix-and-flip or rental opportunities.

7. Close the Deal

Depending on the contract, you’ll either assign the contract (if allowed), do a double closing, or transfer the LLC. Once the deal closes, you collect your wholesale fee, which can range from a few thousand dollars to much more, depending on the property and market.


Challenges and Tips for Wholesaling REO Properties

Wholesaling REOs isn’t as simple as wholesaling privately owned homes, but it’s definitely possible if you’re prepared. Here are some common challenges and how to overcome them:

1. Assignment Restrictions:


Banks often use contracts that prohibit assignment. If you can’t assign, use a double closing or entity assignment. Make sure you have access to funding for the double closing, either your own or through a transactional lender.

2. Larger Deposits Required:


Banks want to see serious buyers, so be prepared to put down a larger earnest money deposit—sometimes up to 10% of the purchase price.

3. No Inspection Periods:


Banks may prefer offers that waive inspections, especially if they’ve had deals fall through before. Only waive inspections if you’re confident about the property’s condition or have done your due diligence.

4. Licensing Requirements:


Check your state’s laws. Some states require wholesalers to be licensed real estate agents, especially if you’re doing multiple deals or advertising the property to the public.

5. Competition:


REO properties attract a lot of attention from investors, so you’ll need to act quickly and make strong offers.

6. Working With Bank Timelines:


Banks can be slow to respond, and their processes are often more rigid than those of private sellers. Be patient but persistent.


Pros and Cons of Wholesaling REO Properties

Let’s break down the main advantages and drawbacks so you know what to expect:

ProsCons
Discounted pricesAssignment often not allowed
Motivated sellers (banks)Larger deposits required
High demand among investorsMay need a license in some states
Potential for quick profitsBanks can be slow and inflexible
No emotional sellersCompetition is fierce

Frequently Asked Questions

Can you wholesale REO properties with no money?

Technically, yes, if you use assignment and the contract allows it. However, with REOs, you’ll often need a larger deposit and may need to fund a double closing, so having access to capital or transactional funding is crucial.

Do you need a real estate license to wholesale REOs?

Not always, but some states require it, especially if you’re doing multiple deals or advertising properties. Always check your local laws and consider working with a licensed broker if needed.

What’s the difference between wholesaling an REO and a traditional property?

With REOs, you’re dealing with banks instead of individuals, which means stricter contracts, less flexibility, and more competition. However, the potential for profit is still strong if you know how to navigate the process.

How do you find buyers for REO wholesale deals?

Build a list of cash buyers—usually investors—before you start. Network at real estate meetups, online forums, and through local agents. The more buyers you have, the faster you can move your deals.


Is Wholesaling REO Properties Right for You?

Wholesaling REO properties is absolutely possible, and many investors have built successful businesses doing just that. The process is a bit more complex than wholesaling privately owned homes, mainly because of bank restrictions and contract terms. If you’re willing to learn the rules, build your network, and act quickly, you can profit from wholesaling REOs.

Remember, success in this niche comes down to preparation, persistence, and understanding both your market and the unique requirements of REO transactions. If you’re ready to put in the work, wholesaling REO properties can be a rewarding way to grow your real estate business and help investors find great deals.

So, can you wholesale REO properties? Yes, you can—and now you know how to get started!

How do I get REO listings from banks?

If you want to find REO (Real Estate Owned) listings from banks, you’re in the right place. REO properties are homes or buildings banks own after foreclosure. They often sell below market value. Many people wonder how to get these listings. Here’s a clear, actionable guide just for you.


What Exactly Is an REO Listing?

An REO listing is a property owned by a bank or lender. This happens after a foreclosure auction fails to sell the home. The bank takes ownership and wants to sell quickly. You can find these properties on bank websites, auction sites, and sometimes even through agents. REO listings are different from regular foreclosures. In a foreclosure, the bank is still trying to take ownership. With REO, the bank already owns the home and wants to sell it.


Where Can You Find REO Listings?

You have several options to find REO listings. The easiest way is to check bank websites directly. Big banks like Wells Fargo, Bank of America, and US Bank often list REO homes online. Local banks and credit unions may also have listings, and sometimes they’re easier to work with. You can also look on REO asset management company sites. Examples include HomePath by Fannie Mae and Freddie Mac’s HomeSteps.

Government agencies like HUD also have REO listings. You can search their websites for available homes. Don’t forget to check your local county’s website. Sometimes, you’ll find REO homes listed under “property search” or “foreclosures for sale”. Even Craigslist and local newspapers sometimes list REO properties. If you want a wider net, check auction sites like Auction.com or Hubzu.

If you’re a real estate agent or work with one, use the MLS (Multiple Listing Service). This database is packed with REO listings. Just remember, not all MLS systems show every listing. For the most complete results, also check realtor.com, Zillow, and Redfin. These sites pull data from many sources and are user-friendly.


How to Get REO Listings Directly from Banks

Getting REO listings directly from banks takes some effort, but it’s worth it. Here’s how you can do it step by step.

1. Identify Banks and Decision-Makers

Start by making a list of banks in your area. Include both big national banks and local ones. Try to find out who handles REO sales at each bank. This could be an asset manager or a special assets officer. The goal is to speak directly to the person who can give you listings.

2. Reach Out and Build Relationships

Once you have your list, contact each bank. Call or email the person in charge of REO sales. Introduce yourself and explain why you’re interested in REO properties. Be friendly and professional. Follow up with a phone call or email a week later. Persistence pays off here.

3. Prepare Your Pitch

While you’re building relationships, get ready for your pitch. Research the local market and know your stuff about foreclosures. Prepare a short presentation about your experience and how you can help the bank sell properties. Highlight what makes you different from other agents or investors.

4. Offer BPO Services

Banks often need Broker Price Opinions (BPOs) to value their REO properties. Offering to do BPOs can get your foot in the door. Once you’re doing BPOs for a bank, you’re more likely to get REO listings when they come up.

5. Network with REO Agents

Banks rely on real estate agents to sell REO properties. Networking with agents who specialize in REO sales can give you early access to listings. These agents often know about new listings before they hit the market.


Tips for Success When Pursuing REO Listings

Here are some extra tips to help you succeed when trying to get REO listings from banks.

  • Be Persistent: Banks get many calls about REO listings. Stand out by following up regularly and being professional.
  • Know the Market: Understand local foreclosure trends and property values. This knowledge will impress bank representatives.
  • Be Flexible: Banks may have strict requirements for buyers or agents. Be ready to adapt and meet their needs.
  • Offer Value: Show the bank how you can help them sell properties faster or at a better price.
  • Stay Organized: Keep track of your contacts, follow-ups, and listings. Organization is key to success.

Common Mistakes to Avoid

Avoid these mistakes if you want to get REO listings from banks.

  • Being Too Passive: Don’t wait for banks to call you. Reach out and take initiative.
  • Not Following Up: One call or email isn’t enough. Follow up regularly to stay on their radar.
  • Lack of Preparation: Don’t pitch to a bank without knowing your market or their needs.
  • Ignoring Local Banks: Big banks are obvious, but local banks often have great deals and are easier to work with.
  • Overlooking Online Resources: Use every tool available, including bank websites, auction sites, and MLS.

So How Do You Get These REO Listings?

Getting REO listings from banks is possible if you’re proactive and persistent. Start by identifying banks and the right contacts. Build relationships and prepare your pitch. Offer BPO services and network with REO agents. Use online resources and stay organized. With these steps, you’ll be well on your way to finding great REO deals.

Remember, banks want to sell these properties. If you show them you’re reliable and knowledgeable, you’ll have a better chance of getting the listings you want. Good luck, and happy house hunting!